If you're earning well but keep wondering whether you need a financial advisor or a financial coach, here's the short answer: a financial advisor manages and sells investments. A financial coach helps you build the habits and system that make your money work in the first place.
Most people actually need a coach first, and an advisor later, once there's real extra income to invest.
That might sound surprising. You may assume that because you earn a good salary, you should already be working with an advisor. Or maybe you've been putting off getting help because you aren't sure whether your finances are “far enough along.”
You’re not behind. You may simply need a clear path and a system that helps you follow through.
Financial advisor vs. financial coach: the basic difference
Both professionals can help you make progress, but they usually help with different parts of your financial life.
Financial Advisor
A financial advisor typically focuses on your investments and long-term wealth management.
- Licensed or registered to provide investment advice or sell investment products, depending on their role and credentials
- May manage your investment portfolio for a fee, sometimes alongside commissions on products they sell
- May provide regular updates on your investments and assets
- Can help with investment selection, retirement planning, and other complex financial decisions
- The right fit once you have extra income or assets and are ready to grow and invest them
The exact services, fees, and legal obligations can vary from one advisor to another. Before working with an advisor, it’s important to ask how they’re paid, what licenses they hold, and whether they act as a fiduciary.
Financial Coach
A financial coach focuses on the day-to-day systems and behaviors that help you manage your money with more confidence.
- Helps change your financial behavior and build your system from the ground up
- Can help you organize cash flow, spending, saving, debt payoff, and financial goals
- Collaborates with you: you make the decisions, since you're the expert on your own life
- Doesn't sell financial products, so the advice has nothing riding on it
- The right fit when you've maxed out free resources, read the books, and still can't make the plan stick
A coach typically does not manage your investment portfolio or recommend specific securities unless they also have the required credentials to do so. The focus is helping you understand your situation, make decisions, and create a workable plan you can actually use.

So which one do you actually need right now?
If your money is already invested and growing, and you need someone managing that portfolio, that's an advisor's job.
If you're making good money but it still doesn't feel like it's going anywhere, if you've tried the budgeting apps and the spreadsheets and they didn't stick, or if you know what you should be doing but can't seem to put it into action alone, that's a coach.
That's most of my clients.
When I ask why they chose coaching over an advisor, the answer I hear most is some version of the same thing: they didn't want to be sold investment products. They wanted someone focused on the budgeting piece. The actual day-to-day system that makes the money work.
You're not behind. You just need a clear path, and that's different from needing someone to manage investments you don't have yet.
You may need a financial coach if…
You might benefit from financial coaching if:
- You make good money but still feel financially disorganized
- You aren't sure where your paycheck goes each month
- You want to create a spending plan that works in real life
- You need to prioritize debt payoff, saving, or competing financial goals
- You have tried budgeting apps, spreadsheets, books, or podcasts but still can’t make the plan stick
- You know what you should be doing but struggle to follow through on your own
- You are going through a major transition, such as buying a home, getting married, having a child, or changing careers
- You want support and accountability without being sold financial products
This isn't about needing more information.
You may already know plenty. The harder part is turning that knowledge into a system that fits your actual income, bills, priorities, and life.
That’s where coaching can help.
You may need a financial advisor if…
An advisor may be a better fit if:
- You have investable assets and want professional portfolio management
- You need specific investment recommendations
- You are preparing for retirement and want help managing a larger investment portfolio
- You have complex tax, estate, insurance, or retirement planning needs
- You want someone to monitor and adjust your investments over time
You may eventually need both types of support.
A financial coach can help you get organized, create room in your cash flow, reduce debt, and build consistent savings habits. Then, once you have meaningful assets or extra income ready to invest, a financial advisor can help you decide how to grow and protect that money.
It’s not always either-or. For many people, it’s a matter of timing.
Will you try to sell me something?
No.
I don't sell financial or insurance products, and I never will.
Some people who call themselves financial coaches use that title to get in the door before pitching annuities or insurance. That's not what happens here. My income comes only from coaching, never from anything I could sell you, so there's nothing shaping my advice except what's actually right for you.
You should always feel comfortable asking any financial professional:
- How are you paid?
- Do you sell financial or insurance products?
- What licenses or certifications do you hold?
- What services are included?
- Will you make decisions for me, or will we make them together?
- What happens if I decide I don’t need additional support?
The right professional should answer clearly and give you space to make an informed decision.
What financial coaching can help you do
Financial coaching is not about handing you another generic budget and telling you to spend less.
It’s about looking at your specific situation and creating a system that helps your money work together.
That may include:
- Organizing your income, bills, and spending
- Creating a paycheck or monthly spending plan
- Setting up automatic savings and bill payments
- Choosing which goals to prioritize first
- Creating a debt payoff strategy
- Building an emergency fund
- Preparing for a major life transition
- Making progress toward homeownership, retirement, or business goals
- Reviewing your progress and adjusting the plan when life changes
A system can reduce the mental load. Instead of wondering what to do every time you get paid, you have a plan for where your money goes and why.
You get less worry, fewer last-minute decisions, and more confidence.
You can also learn more about creating an automated money system in How to Automate Your Finances or start with Organizing Your Financial Life.
What happens when you start with clarity?
You may be feeling overwhelmed because every financial decision seems connected to another one.
Should you pay off debt or invest? How much should you save? Can you afford the upcoming expense? Are you spending too much, or are your goals simply too ambitious for your current system?
You don’t have to solve every question at once.
In a Money Clarity Session, we look at your specific situation, talk through what’s working and what’s not, and identify the decisions or roadblocks keeping you from moving forward.
You leave with two or three specific action steps, not a giant to-do list.
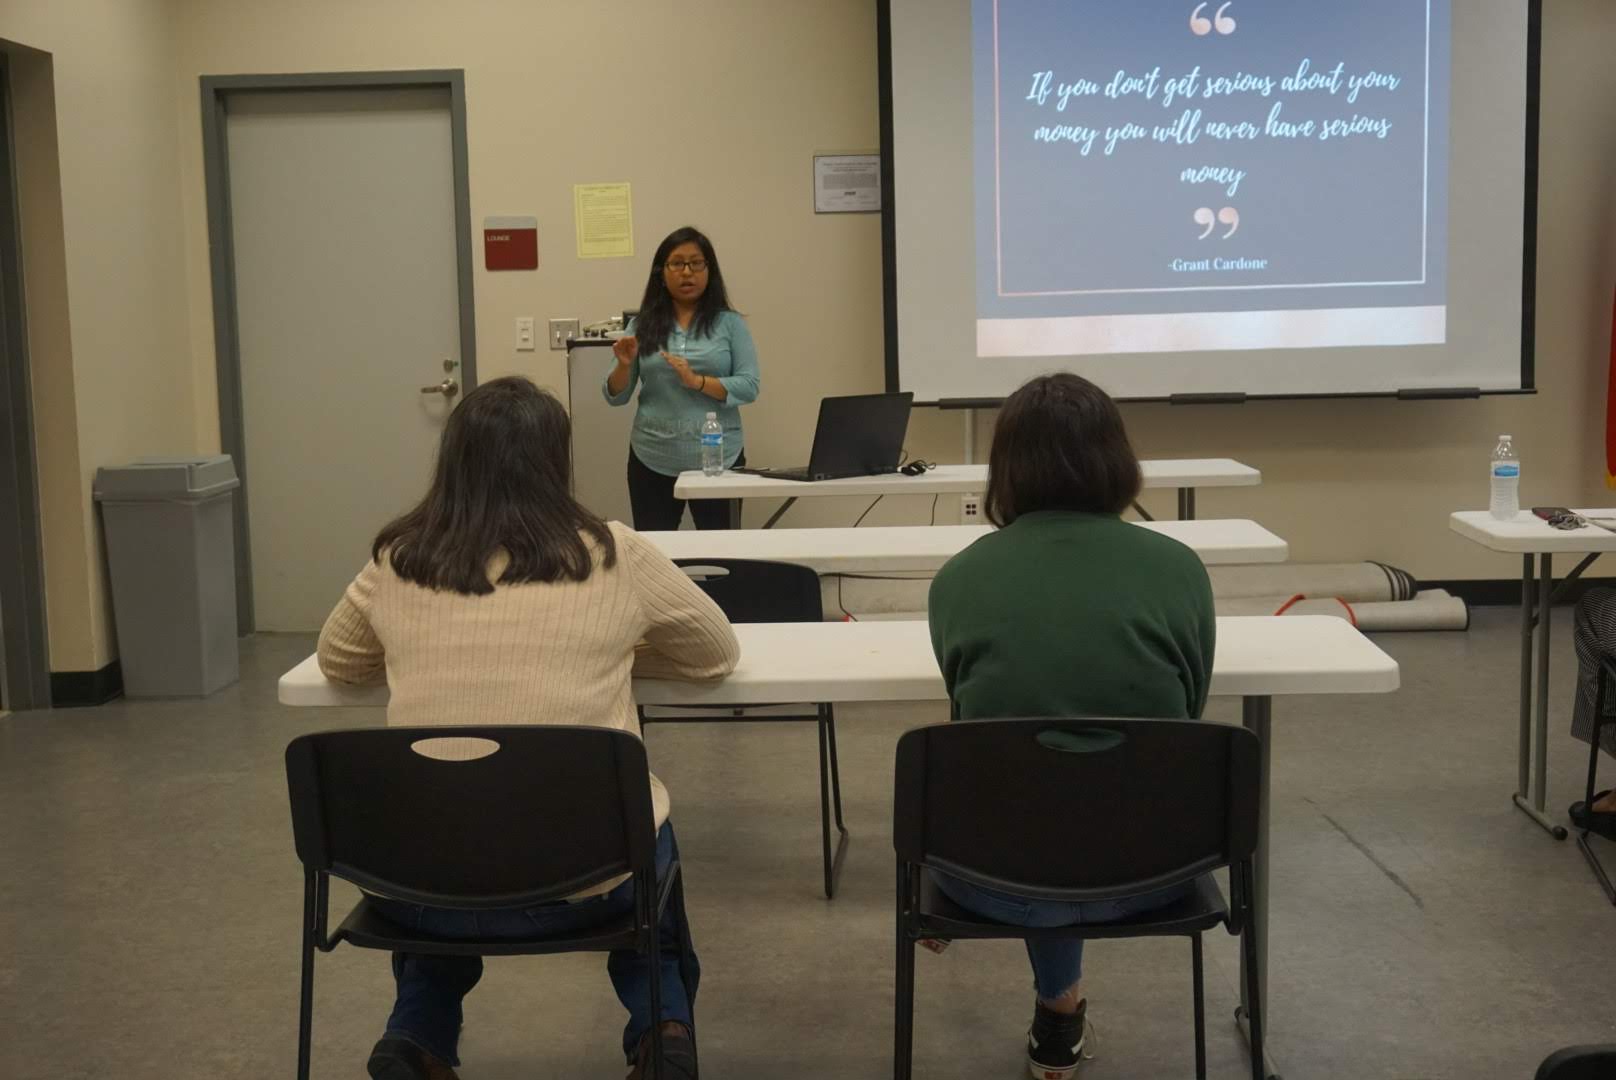
Working with a financial coach in Houston (or anywhere)
I’m based in Houston, Texas, but my coaching is fully virtual, so I work with women here in Texas and well beyond. If you want support, you do not need to be local to get a clear, personalized plan.
If you are in the Greater Houston area, I’m also happy to travel and meet in person for your first session. It’s a warm way to get started, and something I’m glad to offer when it makes the process feel easier and more comfortable for you.
If what you need is investment management or someone to manage a portfolio, a financial advisor is the right fit for that. But if the day-to-day system still feels messy—if your paycheck, bills, spending, and goals are not working together yet—a financial coach is often the best place to start.
The bottom line: start with the help you need now
A financial advisor manages investments.
A financial coach helps you build the financial system that makes those investments, and your other goals, possible.
If your money is already invested and you need portfolio management, an advisor may be the right next step.
If you’re earning well but still feel stuck, disorganized, or uncertain about what to do next, a coach may be the better place to start.
Most people don’t need more pressure. They need support turning information into action.
And you don’t have to commit to ongoing coaching before you understand whether it’s a fit. A free discovery call is an informal way to ask questions, explain what’s going on, and figure out where you actually stand.
No pressure. No pitch.
Schedule your free discovery call
Let’s figure out whether you need a financial coach, a financial advisor, or simply a clearer next step.
This article is for general educational purposes and is not investment, tax, legal, or insurance advice. Financial professionals’ services, credentials, fees, and legal obligations can vary. Review those details carefully before choosing a provider.